
VIDEO
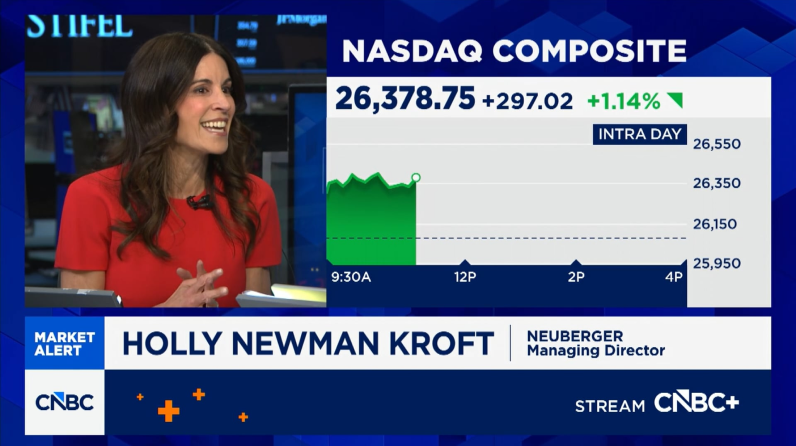
Holly Newman Kroft Featured on CNBC’s Squawk on the Street September 11, 2026
September 15, 2026
The Fed is expected to hike rates on September 16, which may in fact steady the long end of the Treasury curve and continued Fed- and election-related volatility may continue through the start of Q3 earnings season.
U. S. core CPI for August came in hot, up +0.3% month-over-month (MoM) versus +0.2% expected and up +2.4% year-over-year (YoY) – admittedly, this represented the softest YoY move since March 2021. Headline CPI, for its part, was in line, up +0.4% MoM and up +3.4% YoY, rising from +0.1% MoM in July.
Headline CPI reflected the increase of +3.9% MoM for gasoline; the +27.4% YoY increase in gas prices was the primary driver of the +16.3% jump in overall energy over the past year. Grocery prices were mixed for the month, as eggs and dairy were higher while lettuce buyers finally found some relief. Even with food at home flat on the month, overall food prices were up +0.1% as food away from home surged +0.3%. Utility prices also cooled in the month, down -1.1% after an increase of +0.7% in July.
Core CPI, more importantly, came in hot for the month on higher shelter prices, driven by a +2.4% increase in lodging away from home; rents and owners’ equivalent rent were both up +0.2%, down from +0.3%. Airfares were up another +2.7%, with education (+0.8%), communication (+5.4%), and new vehicles (+0.3%) also higher in August while medical care services (-0.2%) and motor vehicle insurance (-0.8%) were lower.
The hotter CPI was corroborated by yesterday’s PPI release, as August headline PPI rose +0.4% MoM (in line with estimates) and +5.4% YoY (versus +0.1% and +5.4%, respectively, in July). The biggest driver of the surge in headline PPI was another spike in energy prices, but even stripping that out, core PPI was up +0.3% as a tick-up in goods prices and a pop in transportation and warehousing overwhelmed tempered services inflation.
While we admit that supply shocks typically produce shorter duration inflationary effects, the continuation of the conflict in the Middle East complicates the current narrative. Passthrough of these higher costs has been up to this point limited, but the move higher in goods indicates that it could be accelerating. In addition, the potential for AI-related spending to push prices higher across a broader set of inputs could exacerbate the problem, offsetting the continued moderation in wage growth and shelter prices for which the Fed has been patiently waiting.
This threat is what the Fed will be weighing going into their next meeting. Loathe to react to a short-term oil supply shock, the FOMC voters instead will evaluate the likelihood for further passthrough, and perhaps more importantly, the growth potential for the economy and the AI ecosystem in particular. As such, we believe the Fed is likely to hike rates on September 16, which may in fact steady the long end of the Treasury curve. In terms of reaction, the increase in the probability of a rate hike to over 90% today was well digested by equity and bond investors, who likely positioned ahead of the release for an in line or above target print. Investors were also likely comforted by a move lower in oil prices despite a strengthening Houthi advance in Yemen. As we relayed in our last update, we believe that both Fed and election related volatility could continue through the start of Q3 earnings season and encourage investors to review their overall asset allocations and take advantage of any pullbacks to position their portfolios ahead of the U.S. midterm elections.


IMPORTANT INFORMATION:
This material is provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. This material is general in nature and is not directed to any category of investors and should not be regarded as individualized, a recommendation, investment advice or a suggestion to engage in or refrain from any investment-related course of action. Any views or opinions expressed may not reflect those of the firm as a whole. Neuberger products and services may not be available in all jurisdictions or to all client types. Diversification does not guarantee profit or protect against loss in declining markets. Investing entails risks, including possible loss of principal. Investments in private equity are speculative and involve a higher degree of risk than more traditional investments. Investments in private equity are intended for sophisticated investors only. Unless otherwise indicated, returns shown reflect reinvestment of dividends and distributions. Indexes are unmanaged and are not available for direct investment. Investing entails risks, including possible loss of principal. Past performance is no guarantee of future results.
Portfolio positioning views expressed herein are those of Neuberger’s Wealth Investment Group, which may include those of the Neuberger’s Asset Allocation Committee. Asset allocation and positioning views are based on a hypothetical reference portfolio. The Wealth Investment Group analyzes market and economic indicators to develop asset allocation strategies. The Wealth Investment Group works in partnership with the Office of the CIO. The Wealth Investment Group also consults regularly with portfolio managers and investment officers across the firm. The Asset Allocation Committee is comprised of professionals across multiple disciplines, including equity and fixed income strategists and portfolio managers. The Asset Allocation Committee reviews and sets long-term asset allocation models, establishes preferred near-term tactical asset class allocations and, upon request, reviews asset allocations for large, diversified mandates. Asset Allocation Committee members are polled on asset classes and the positional views are representative of an Asset Allocation Committee consensus. The views of the Asset Allocation Committee and the Wealth Investment Group may not reflect the views of the firm as a whole and Neuberger advisers and portfolio managers may take contrary positions to the views of the Asset Allocation Committee or the Wealth Investment Group. The Asset Allocation Committee and the Wealth Investment Group views do not constitute a prediction or projection of future events or future market behavior. Defensive positioning generally means an underweight bias on allocations to risk assets such as equities and alternatives. Positioning views may change over time without notice and actual client positioning may vary significantly. Discussion of yield characteristics or total returns of different asset classes are for illustrative purposes only. Such asset classes, such as equities and fixed income, may have significantly different overall risk-return characteristics which should be consider before investing.
The information in this material may contain projections, market outlooks or other forward-looking statements regarding future events, including economic, asset class and market outlooks or expectations, and is only current as of the date indicated. There is no assurance that such events, outlook and expectations will be achieved, and actual results may be significantly different than that shown here. The duration and characteristics of past market/economic cycles and market behavior, including any bull/bear markets, is no indication of the duration and characteristics of any current or future be market/economic cycles or behavior. Information on historical observations about asset or sub-asset classes is not intended to represent or predict future events. Historical trends do not imply, forecast or guarantee future results. Information is based on current views and market conditions, which will fluctuate and may be superseded by subsequent market events or for other reasons.
Discussions of any specific sectors and companies are for informational purposes only. This material is not intended as a formal research report and should not be relied upon as a basis for making an investment decision. The firm, its employees and advisory accounts may hold positions of any companies discussed. Nothing herein constitutes a recommendation to buy, sell or hold a security. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. Investment decisions and the appropriateness of this content should be made based on an investor's individual objectives and circumstances and in consultation with his or her advisors.
Neuberger Investment Advisers LLC is a registered investment adviser.
The “Neuberger” name and logo are registered service marks of Neuberger Berman Group LLC.